
A modern car contains more computing power than the Apollo programme, and it is not unusual about it: phones, washing machines, tractors, pacemakers and power grids all run on semiconductors. These thumbnail-sized circuits have become the foundational commodity of the century — which is why their supply, concentrated in a handful of places, now occupies finance ministries as much as engineering faculties.
How a chip gets made
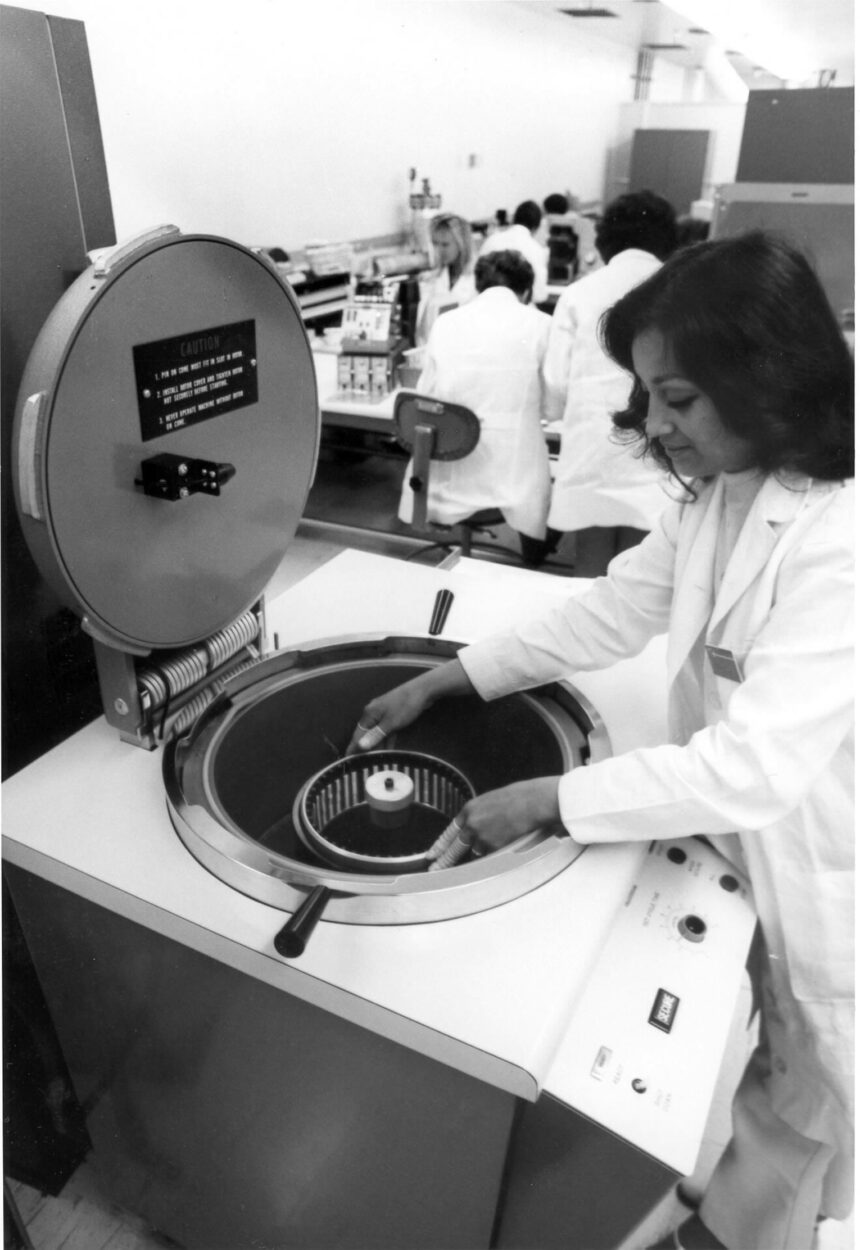
Fabrication begins with near-perfect silicon wafers, onto which patterns are printed with ultraviolet light in dozens of layered steps — depositing, etching and doping until billions of transistors stand in formation. The most advanced lithography machines, built by a single Dutch company, use droplets of molten tin and mirrors polished to atomic smoothness. A leading-edge plant costs upwards of twenty billion dollars and years to bring to full yield.
For more coverage of the stories shaping the day, visit our homepage and the latest reporting in News.
Why supply concentrated
Concentration was an outcome of economics, not conspiracy: the capital and expertise required are so extreme that only a few firms and regions could sustain them, and customers benefited from the resulting efficiency. The vulnerability became obvious when demand whipsawed during the pandemic. The policy response — subsidies across the US, Europe, Japan, India and elsewhere — is an attempt to buy redundancy, accepting higher costs as an insurance premium.
The AI demand shock
Artificial intelligence has added a second scramble on top of the first: advanced accelerators for training and running models are now the industry’s most contested product, with their own exotic supply chain of high-bandwidth memory and advanced packaging. Data centre construction is being paced by chip availability and electricity supply together — a strange sentence that would have baffled planners a decade ago and now appears in utility filings.
Further reading: OECD work on semiconductor value chains.
Not all chips are cutting-edge
Most of the world’s chips are “mature” — larger, older designs that run cars, appliances and industry perfectly well, made in different plants under different economics. Policy that fixates only on the frontier misses where shortages actually bite. A resilient strategy needs both: frontier capacity for computing’s future and boring, abundant capacity for the machinery of daily life.
Talent is the slowest input
Plants can be subsidised into existence faster than workforces can be trained. Process engineers, clean-room technicians and equipment specialists take years to develop, and every region building fabs is competing for the same scarce people. Universities and technical colleges have become quiet bottlenecks in a very loud industrial race — and, for students choosing careers, an unusually reliable signal of demand.
Understanding the chip race
- Leading-edge plants cost tens of billions and years to build.
- Most chips in daily life are mature designs, not frontier ones.
- AI accelerators have created a second, parallel scramble.
- Trained engineers are the scarcest input of all.
Why this matters now
Semiconductors have become the measure of technological sovereignty, and the subsidy race they triggered is the largest industrial policy intervention since the space age. Its consequences will not be confined to chip firms: car makers, defence planners, hospitals and cloud companies all now plan around silicon supply. For the wider public, the chip era has a quieter meaning — the devices of daily life depend on a global system of extraordinary sophistication and surprising fragility, and understanding that system has become part of economic literacy.
Chips are where the physical and digital economies meet, and their supply is now treated — correctly — as critical infrastructure. The race to make more of them, in more places, will shape industrial geography for a generation.